RAK Property Market 2026: Can Wynn Absorb 13,800 New Homes?
Ras Al Khaimah’s residential market has reached a more complicated stage of its growth cycle. Apartment prices were still 6.5% higher year-on-year in H1 2026, while villa prices were up by almost 6%. Rents also remained above their 2025 levels. Yet the latest quarterly data moved in the opposite direction, with apartment sale prices falling 0.7%, villa prices slipping 0.2% and apartment rents declining 1.4% over the most recent three-month period.
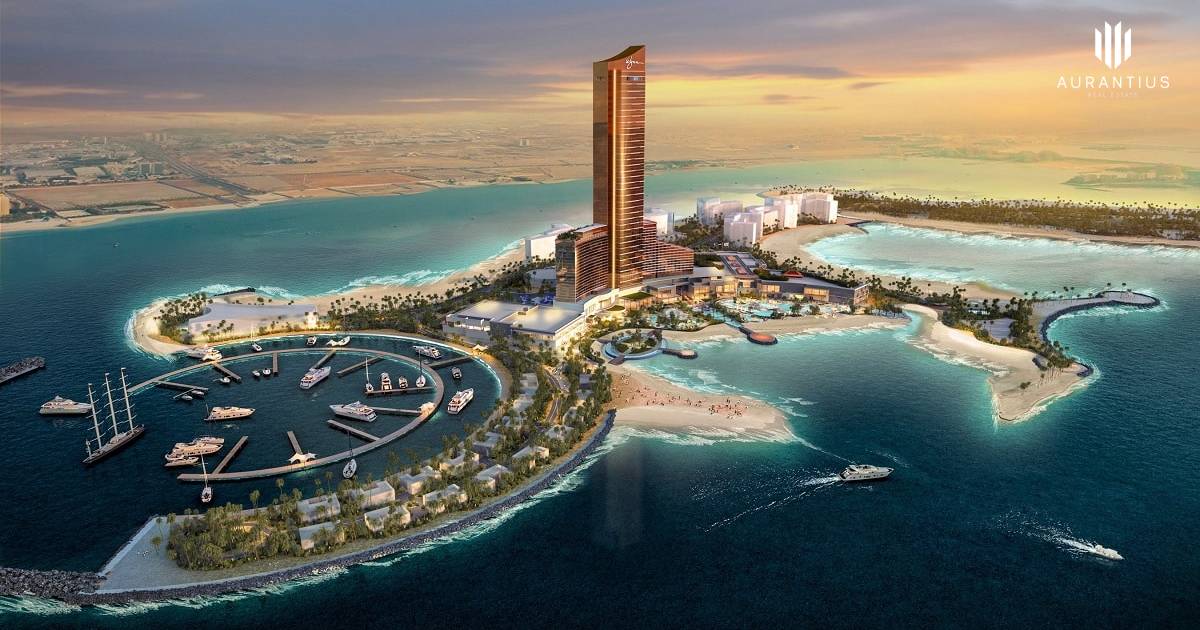
At the same time, approximately 13,800 new homes are expected to enter the Ras Al Khaimah market by the end of 2028. This incoming supply arrives just as Wynn Al Marjan Island moves toward its now-confirmed September 2027 opening.
That combination creates the real 2026 investment question. The issue is no longer whether Ras Al Khaimah has attracted international attention. It clearly has. The question is whether tourism, employment, population growth and genuine end-user demand can absorb thousands of new homes without the market becoming dependent on increasingly optimistic off-plan resale expectations.
The 2026 RAK investment thesis: The market is not showing evidence of a broad collapse. It is showing early moderation at the same time that supply is accelerating. That shifts the advantage toward buyers who compare projects carefully rather than assuming every property near Wynn or Al Marjan Island will appreciate at the same rate.
RAK Prices Are Still Up Annually, but the Quarterly Direction Has Changed
The first mistake investors should avoid is describing Ras Al Khaimah’s market as either simply “booming” or simply “falling”. Both descriptions miss the current data.
| RAK Residential Metric | H1 2026 Annual Change | Latest Quarterly Change |
|---|---|---|
| Apartment sale prices | +6.5% YoY | -0.7% |
| Villa sale prices | Almost +6% YoY | -0.2% |
| Apartment rents | More than +7% YoY | -1.4% |
| Villa rents | +8% YoY | Nearly +1% |
This is best described as moderation after strong growth. Annual values remain higher because the market entered 2026 from a stronger base, while more recent data suggests buyers and tenants are becoming more selective.
That is an important change from the earlier phase of the RAK cycle, when investor demand was accelerating rapidly. Aurantius covered that stage in Ras Al Khaimah Market Surges With Investor Demand. The 2026 market now requires a more selective approach.
13,800 New Homes Are the Most Important Number in the Market
Ras Al Khaimah’s supply pipeline is substantial relative to the size of its existing freehold residential sector.
Current forecasts indicate:
| Year | Expected Residential Deliveries |
|---|---|
| 2026 | Approximately 2,200 homes |
| 2027 | Approximately 4,700 homes |
| 2028 | Approximately 7,500 homes |
| Total through end-2028 | Approximately 13,800 homes |
Around 600 units were delivered in H1 2026, with approximately 1,600 additional homes expected during the second half of the year.
These figures are forecasts rather than guaranteed handover totals. Construction schedules can move, projects can be phased differently and delivery timing may change. But even allowing for slippage, the direction is clear: RAK buyers will have considerably more choice.
More Supply Changes Developer Pricing Power
Incoming supply does not automatically cause a price crash. Its first effect is usually competition.
When buyers can compare multiple new projects targeting similar investors, developers have to compete harder on:
• entry price;
• payment plans;
• design and finishing;
• brand partnerships;
• beachfront positioning;
• amenities;
• handover certainty; and
• incentives.
This is why a large supply pipeline can be positive for disciplined buyers even if it moderates headline price growth.
The investor’s objective is not necessarily to find the market with the least supply. It is to find a property where future demand is likely to exceed the relevant competing supply at the price paid.
The Wynn Demand Test Starts Before September 2027
Wynn Resorts confirmed in its Q2 2026 results that Wynn Al Marjan Island is expected to open in September 2027.
The development is strategically important because it can generate multiple types of property demand rather than only tourist arrivals.
Potential demand channels include:
• direct resort employment;
• supplier and service employment;
• hospitality and retail activity;
• international tourism;
• second-home demand;
• luxury residential demand; and
• potential short-term accommodation demand in surrounding locations.
However, the Wynn effect should not be interpreted as unlimited demand for every new apartment launched on or near Al Marjan Island.
A resort can create thousands of reasons to visit or work in an area without ensuring that every investor-owned unit achieves the rent, occupancy or resale price assumed at launch.
Al Marjan Island Faces the Highest Potential Reward and the Highest Expectation Risk
Al Marjan Island sits at the centre of the Wynn narrative. Its investment proposition benefits from a combination of beachfront scarcity, luxury hospitality, branded residences and the future integrated resort.
But it is also the part of RAK where expectations can become most aggressively priced into off-plan property.
An investor buying on Al Marjan Island should therefore distinguish three values:
1. Today’s underlying property value
+
2. Legitimate beachfront / brand / scarcity premium
+
3. Future Wynn expectation already embedded in the price
The third component is where investment risk increases. If the buyer pays today for years of anticipated future appreciation, Wynn can open successfully and the property can still produce a disappointing return because too much future value was already included in the acquisition price.
The Wynn Bridge Is an Infrastructure Signal, Not a Return Guarantee
Accessibility is also improving around the resort zone. The new bridge connection serving Wynn Al Marjan Island is important because large hospitality developments require reliable movement of visitors, workers, suppliers and residents.
Aurantius covers that infrastructure development separately in the new bridge connecting Wynn Al Marjan Island with the wider road network.
For a property investor, improved access can support the area’s operational maturity. But the bridge should be treated as one demand-supporting factor alongside actual employment, tourism, residential absorption and competing supply.
Ready-Property Transactions Show Buyers Are Still Active
The ready market provides another useful signal.
Freehold ready residential transactions reached AED625.2 million in H1 2026.
That was:
• 24% higher than H2 2025; but
• 3.3% lower than H1 2025.
Q2 activity was stronger than Q1, with transaction value approaching AED354 million.
These numbers are useful because they indicate that buyers are still transacting in completed stock even while prices show some quarterly moderation.
But there is an important dataset warning: AED625.2 million represents ready freehold residential transactions in the dataset being discussed. It should not be presented as total Ras Al Khaimah real estate transaction value across all off-plan sales, mortgages, assignments and property sectors.
Ready Property vs Off-Plan: 2026 Changes the Calculation
| Factor | Ready Property | Off-Plan Property |
|---|---|---|
| Rent evidence | Can assess existing achievable rent | Future rent must be estimated |
| Cash flow | Potentially immediate | Usually begins after handover |
| Supply risk | Known existing competition | May complete alongside thousands of competing units |
| Payment flexibility | Typically lower | Often stronger developer payment options |
| Wynn exposure | Can acquire before resort opening with current rental evidence | Greater dependence on future delivery and future market conditions |
Neither category is automatically better. In a supply-heavy environment, the correct comparison is the price and risk-adjusted return available from each asset.
RAK’s Demand Story Is Bigger Than Wynn
Wynn receives much of the attention, but relying on one resort to justify an entire emirate’s property market would be a weak investment thesis.
Residential absorption will also depend on:
• business formation;
• employment growth;
• tourism expansion;
• new hotels and hospitality businesses;
• population retention;
• infrastructure investment; and
• the emirate’s ability to attract permanent residents rather than only investors.
This broader expansion is part of the UAE-wide investment cycle discussed in UAE Real Estate Market Maintains Momentum Amid Expansion and Innovation.
Does the Quarterly Dip Create a Buying Opportunity?
Possibly, but calling every price decline a buying opportunity is too simplistic.
A 0.7% quarterly apartment-price decline is small compared with the previous annual increase. It may represent normalization after rapid growth rather than a deep correction.
The real advantage for buyers could come from greater negotiating power and project choice, not necessarily from a dramatic fall in headline prices.
For example, increased competition may produce:
• more flexible payment structures;
• better launch incentives;
• stronger negotiation in the secondary market;
• reduced urgency to buy immediately; and
• clearer differentiation between strong and weak projects.
How RAK Compares With Dubai and Other UAE Property Markets
RAK’s appeal differs from Dubai’s.
Dubai has a much deeper completed housing market, broader employment base, larger tenant pool and greater transaction liquidity. Ras Al Khaimah offers a smaller market where major hospitality and infrastructure catalysts can potentially have a larger proportional impact.
That creates both upside and concentration risk.
Investors choosing between emirates can review Aurantius’ Dubai vs Abu Dhabi vs Sharjah vs Ras Al Khaimah property comparison.
RAK has also been identified among the UAE’s emerging investment locations in Aurantius’ UAE property investment hotspots analysis.
The RAK 2026 Investor Stress Test
1. Remove Wynn from the calculation.
Would you still buy the property at today’s price if Wynn’s opening had no immediate effect on your rent or resale value?
2. Compare competing 2027 and 2028 supply.
Identify how many similar apartments or villas may be delivered around your expected handover date.
3. Separate ready-market evidence from off-plan marketing.
Use achieved rents and completed transactions where possible rather than relying only on projected values.
4. Stress-test occupancy.
If your projected holiday-home occupancy or long-term rent is lower than expected, does the investment still work?
5. Check the payment-plan concentration.
Make sure large instalments or handover payments do not force you to resell at an inconvenient time.
6. Calculate the premium for Al Marjan proximity.
Compare the target unit with alternatives in other RAK communities and determine how much extra you are paying for the Wynn narrative.
7. Plan the exit buyer.
Know whether your likely future buyer is an end user, second-home owner, holiday-home investor or another speculative off-plan investor.
FAQ: Ras Al Khaimah Property Market 2026
Question: Are Ras Al Khaimah property prices falling in 2026?
Answer: Prices remained higher year-on-year in H1 2026, with apartments up 6.5% and villas up almost 6%. However, the latest quarterly figures showed small declines of 0.7% for apartments and 0.2% for villas, indicating moderation rather than a confirmed broad downturn.
Question: How many new homes are expected in RAK by 2028?
Answer: Current forecasts indicate approximately 13,800 residential units through the end of 2028, including about 2,200 in 2026, 4,700 in 2027 and 7,500 in 2028. These are forecast delivery figures and actual timing can change.
Question: When will Wynn Al Marjan Island open?
Answer: Wynn Resorts stated in its Q2 2026 results that Wynn Al Marjan Island is currently expected to open in September 2027.
Question: Will Wynn automatically increase Al Marjan Island property prices?
Answer: No. Wynn can support tourism, employment and housing demand, but property performance will still depend on entry price, competing supply, rental demand, product quality and how much of the Wynn premium is already reflected in today’s price.
Question: Is Al Marjan Island still a good investment in 2026?
Answer: It can be attractive for investors seeking beachfront, hospitality and Wynn-linked exposure, but project selection and entry price are increasingly important as more units enter the market. The island should not be treated as one uniform investment.
Question: Is ready property safer than off-plan property in RAK?
Answer: Ready property provides clearer evidence of current rent, occupancy and building quality, while off-plan can offer newer stock and flexible payment plans. The better choice depends on the price, holding period, developer risk and expected supply at handover.
Question: Could 13,800 new units cause a RAK property crash?
Answer: The supply pipeline increases competition and could moderate price and rental growth, but supply alone does not prove a crash. The outcome depends on delivery timing, job creation, tourism, population growth and how effectively the emirate absorbs new residents.
Conclusion: RAK’s Next Phase Will Be Decided by Absorption, Not Launch Hype
Ras Al Khaimah enters the second half of 2026 with stronger property values than a year ago, active ready-property transactions and one of the UAE’s most important upcoming tourism developments approaching completion.
At the same time, the latest quarter has produced the first meaningful signs that the pace of growth is moderating.
That is not necessarily negative. A market where buyers have more choice, developers face more competition and pricing becomes more rational can be healthier than one driven entirely by scarcity and speculative urgency.
The biggest test is the 13,800-home pipeline. If employment, tourism, population and business growth absorb those units while Wynn Al Marjan Island begins operating in September 2027, Ras Al Khaimah could move from a predominantly catalyst-driven investment story toward a deeper functioning residential and hospitality market.
If supply arrives faster than end-user and tenant demand, investors may instead face stronger competition, slower rent growth and greater pressure on projects that were sold at aggressive off-plan premiums.
For Al Marjan Island in particular, Wynn remains a powerful catalyst, but its success does not remove the need to analyse each property’s price, developer, delivery date, view, operating cost and competing inventory.
The 2026 RAK buyer rule: Do not buy because Wynn is coming. Buy because the property works at today’s price, survives the incoming supply test and has a credible tenant or end-user market. If Wynn then strengthens demand after September 2027, treat that as additional upside rather than the only reason the investment succeeds.
Market note: Price, rental, transaction and supply figures in this analysis reflect H1 2026 market research and current September 2026 information. Supply forecasts and project delivery dates can change. Wynn Resorts currently expects Wynn Al Marjan Island to open in September 2027. Property returns, rental demand and capital appreciation are not guaranteed.