Dubai Residential Handovers 2026: Are 38,000 New Homes Putting Pressure on Property Prices?
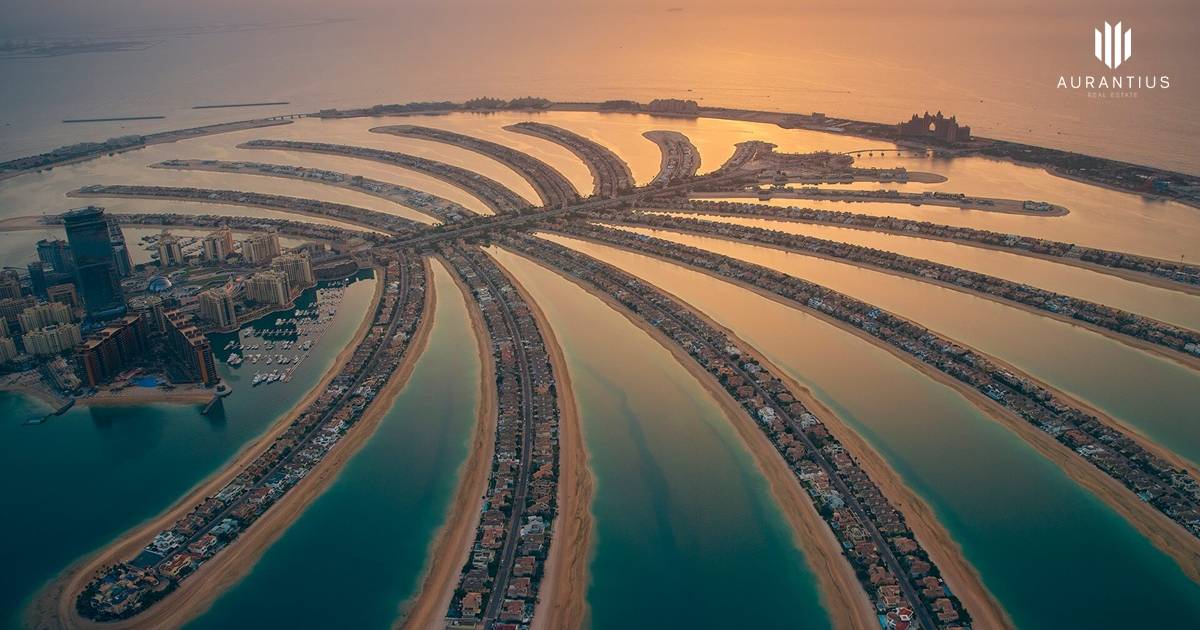
Dubai’s residential market entered a decisive supply phase in 2026. Approximately 38,000 new homes were delivered between January and September, representing a 41.4% increase from the same period in 2025 and already exceeding the full-year delivery totals recorded in both 2023 and 2024.
Around 12,400 homes were completed during Q3 alone, while another 24,400 units were scheduled for the final quarter of the year.
But that final number requires an important qualification. Cavendish Maxwell expects only around 7,300 to 12,200 of those remaining scheduled units to materialise before year-end based on historical delivery patterns. Scheduled handovers and homes that actually become available for occupation are therefore not the same thing.
The supply increase is nevertheless large enough to affect market behaviour. Dubai’s average residential sales price was approximately AED 1,644 per sq. ft. in September 2026, 2.2% below a year earlier, while rental growth has slowed sharply and more tenants are renewing at unchanged or lower rents.
This is evidence of a market adjustment, but not evidence that every Dubai property is falling equally. High-supply apartments, scarce family homes, established ready properties and luxury assets can now produce materially different outcomes.
Dubai Residential Market — Q3 2026 Snapshot
Homes delivered Jan–Sep: Approx. 38,000
Year-on-year delivery growth: +41.4%
Q3 handovers: Approx. 12,400
Additional Q4 scheduled supply: Approx. 24,400 homes
Expected Q4 actual completion range: Approx. 7,300–12,200
September average sales price: AED 1,644/sq. ft.
Sales-price change: −2.2% YoY
Average gross yields: 6.6% apartments / 4.9% villas & townhouses
38,000 Handovers Are Already More Than Dubai Delivered in Full-Year 2023 or 2024
The scale of the 2026 delivery cycle is what makes the latest data important.
Dubai has spent several years operating with rapid population growth, rising rents and strong investor demand. That environment allowed many buildings and communities to absorb new supply without immediately creating strong pricing competition.
The balance changes as thousands of homes move simultaneously from construction sites into the ready market.
A completed unit can become an owner-occupied residence, enter the long-term rental market, become a holiday home or be offered for resale. Every handover therefore potentially adds another option for tenants and buyers.
Aurantius’ Dubai Property Supply Stress Test 2026 explains why the number of comparable homes arriving in the same community is usually more important to an individual investor than the citywide supply headline.
Scheduled Supply Is Not the Same as Actual Supply
A frequent mistake in Dubai real estate analysis is adding every developer completion target together and treating the result as guaranteed inventory.
The Q3 data provides a useful reality check.
| Supply Measure | Q4 2026 Position |
|---|---|
| Units scheduled after September | Approx. 24,400 |
| Expected actual completions | Approx. 7,300–12,200 |
| Why the difference? | Construction timing, approvals, commissioning and project-specific delivery slippage |
For off-plan buyers, this distinction can materially affect financial planning. Aurantius’ Dubai Off-Plan Handover Delays 2026 guide explains why the advertised completion date, main construction completion and final key handover should not automatically be treated as the same milestone.
Dubai Property Prices Have Started to Reflect the More Balanced Market
Cavendish Maxwell’s Q3 market data shows average residential sales prices at approximately AED 1,644 per sq. ft. in September.
That was 2.2% lower than September 2025, representing the first annual decline since the post-pandemic recovery began. Prices had moved into negative annual territory in August.
At the same time, prices increased approximately 0.3% quarter-on-quarter.
Those two numbers illustrate why “Dubai prices are falling” is too simplistic. Annual pricing has softened, but the market was not moving continuously downward during Q3.
| Q3 2026 Sales Metric | Result |
|---|---|
| Residential sales value | AED 72.6B |
| Residential transactions | 33,900 |
| Value vs Q2 | −13.2% |
| Volume vs Q2 | −2.0% |
| Value vs Q3 2025 | −47.6% |
| Volume vs Q3 2025 | −38.6% |
The wider context is covered in the Dubai Real Estate Forecast 2026 Heading Into Q4, where the central investment question has shifted from forecasting one citywide growth percentage to assessing the competitiveness of an individual property.
The Rental Market Shows the Supply Effect Even More Clearly
The strongest evidence of the changing supply-demand balance may be in tenancy renewals.
During Q3 2026, 21.4% of rental transactions were agreed at a lower rent than the previous contract. That compares with only 4.8% in Q1.
Another 38.7% renewed at the same rent, while the share recording an increase fell to 40% from 59.4% at the beginning of the year.
| Q3 2026 Rental Outcome | Share |
|---|---|
| Rent lower than previous contract | 21.4% |
| Rent unchanged | 38.7% |
| Rent increased | 40.0% |
This does not mean Dubai rents are universally declining. Average residential rent still stood at approximately AED 77.3 per sq. ft. per year in September, 5.5% higher year-on-year.
The important change is the pace. Annual rental growth was 11.5% in September 2025, meaning growth has slowed substantially as tenants gain more alternatives.
Aurantius’ Dubai Rental Market 2026 report shows how this competition is already producing very different asking-rent outcomes between communities.
New Rental Contracts Are Growing While Renewals Decline
More than 172,000 rental contracts were registered during Q3.
Renewals fell 10.6% year-on-year to approximately 94,300, while new rental contracts increased 18.2% to around 77,700.
This can be consistent with a market where tenants have more choices. Some occupants are staying and negotiating more favourable renewal terms; others are moving into newly available stock.
For landlords, the calculation increasingly becomes one of occupancy versus headline rent. A small rent concession can be financially preferable to several weeks of vacancy if numerous comparable units are competing for the same tenant.
Rental Yields Remain Attractive Despite Softer Conditions
The increase in supply has not eliminated Dubai’s income-investment case.
Cavendish Maxwell placed average Q3 gross rental yields at approximately 6.6% for apartments and 4.9% for villas and townhouses.
| Property Segment | Average Q3 Gross Yield |
|---|---|
| Apartments | 6.6% |
| Villas & townhouses | 4.9% |
Among apartment communities in the Q3 research, Dubai Investments Park recorded a 10% gross yield, followed by International City at 9% and Dubai Production City at 8%.
For villas and townhouses, Dubai Industrial City recorded 6.5%, Jumeirah Golf Estates 5.8% and DAMAC Hills 2 approximately 5.7%.
Those are gross figures. Investors still need to deduct service charges, maintenance, management, vacancy and financing before comparing the property with another investment asset.
For that reason, Aurantius’ Dubai Real Estate ROI 2026 guide focuses on the difference between headline yield and the income an owner actually retains.
Ready Properties Are Gaining Momentum as Off-Plan Sales Cool
Q3 also showed an important shift in transaction composition.
Off-plan remained dominant with approximately 24,500 sales worth AED 47.1 billion, representing 72.2% of Q3 transactions. However, off-plan deal volume was 41.9% lower than a year earlier.
Ready-property sales moved in the opposite direction quarter-on-quarter, increasing 19.7% from Q2 to approximately 9,400 transactions, although they remained below Q3 2025 levels.
The October data subsequently reinforced that ready-market momentum. Aurantius’ Dubai Ready Apartment Sales October 2026 report recorded AED 5.28 billion across 2,988 completed apartment transactions in the following month.
Developers Are Also Reducing the Pace of New Launches
Supply pressure is not only affecting buyers and tenants. Developers are adjusting too.
Dubai recorded 48 new residential projects containing approximately 15,300 units in Q3 2026.
Compared with Q3 2025, the number of projects launched declined 72.7% and the number of units launched fell 62.9%.
Across the first nine months, around 190 projects containing 49,800 homes were launched, also substantially below the comparable 2025 period.
Cavendish Maxwell attributed part of the contraction to greater developer caution and regional uncertainty. From an investment perspective, it also means the market is moving from a launch-heavy cycle toward a much larger test of construction execution and absorption.
The Bigger Supply Test Comes in 2027 and 2028
The 38,000 units delivered by September are significant, but they are only part of the pipeline currently scheduled.
| Period | Scheduled Residential Supply |
|---|---|
| Rest of 2026 | 24,400 |
| 2027 | 136,100 |
| 2028 | 155,700 |
| 2027 + 2028 | 291,800 |
Those are scheduled figures, not guaranteed completed homes. Actual absorption will depend on how many units physically hand over and how quickly population growth, employment and household formation create demand for them.
Which Properties Are Most Exposed to the Handover Wave?
The strongest supply pressure usually occurs where multiple new properties are close substitutes for one another.
A one-bedroom apartment can face intense competition when thousands of similar one-bedroom units are delivered within the same investment corridor. A rare villa, large upgraded residence or genuinely differentiated waterfront home may have fewer substitutes even during a high-supply year.
| Property Characteristic | Supply-Risk Interpretation |
|---|---|
| Generic apartment with many new substitutes | Higher rent and resale competition |
| Established building with proven rent | Easier to assess, but must compete with newer inventory |
| Scarce villa or differentiated large home | Fewer direct substitutes can improve resilience |
| Premium property bought at excessive price | Scarcity cannot compensate automatically for overpayment |
The “Handover Squeeze” Can Create Both Risk and Opportunity
An off-plan investor reaching handover can face several cash requirements at approximately the same time: outstanding contractual payments, mortgage or refinancing decisions, furnishing, service-charge payments and the cost of preparing the property for rental.
If a large number of investors in the same development are also attempting to rent or resell units, landlords and sellers may need to compete more aggressively.
That can create opportunity for buyers with available capital, but the term “distressed” should not be applied automatically. A seller accepting a smaller premium or negotiating at handover is not necessarily in financial distress.
The opportunity comes from identifying motivated pricing while confirming that the underlying building, rent and future supply remain competitive.
How to Read a 5-Year Property vs Fixed-Yield Investment Projection
A five-year return comparison can be useful, but only when the assumptions behind the visual are clear.
In the supplied illustrative projection, the property produces a fixed annual rental return that accumulates to approximately AED 250,000 over five years, while the alternative fixed-yield asset reaches approximately AED 275,000 through a slightly compounding return structure.
That chart should not be interpreted as a forecast that a financial asset will outperform Dubai property.
The property illustration excludes: capital appreciation or depreciation
It also excludes: service charges, maintenance, vacancy and management
Financing: Mortgage interest can materially change cash-on-cash return
Alternative investment: Fixed yields may not remain fixed for five years unless contractually locked
Correct use: Treat the chart as a scenario comparison, not a market forecast
Mortgage Cost Matters More When Appreciation Slows
When investors could assume rapid price appreciation, financing costs were sometimes treated as a secondary issue. A more balanced market makes that approach riskier.
A financed investor should calculate the monthly loan payment, service charges, property insurance where applicable, maintenance, vacancy and acquisition costs before comparing the investment with an unleveraged financial asset.
The supplied mortgage-calculator visual should be treated as an illustrative financing interface rather than a Dubai bank quote. It uses generic terminology and currency formatting, so investors should replace its assumptions with an actual UAE lender quotation and the specific property’s service charges before making a decision.
2026 Buyer Stress Test: Would the Property Still Work Without Appreciation?
1. Remove capital appreciation from the first three years of your model.
2. Reduce expected rent by 5% and test the result again.
3. Include at least a realistic vacancy allowance.
4. Deduct service charges, management and maintenance.
5. Count comparable units completing before your expected resale date.
6. Compare the unit with ready alternatives producing rent immediately.
7. Confirm that any large handover payment can be funded without relying on a quick resale.
8. Buy only if the investment still works under the weaker scenario.
FAQ: Dubai Property Handovers & Supply in 2026
Question: How many new homes were delivered in Dubai in the first nine months of 2026?
Answer: Approximately 38,000 residential units were delivered between January and September 2026, around 41.4% more than during the same period in 2025.
Question: Will another 24,400 homes definitely be delivered by the end of 2026?
Answer: No. Around 24,400 are scheduled, but Cavendish Maxwell expects actual Q4 completions of approximately 7,300 to 12,200 based on historic materialisation rates.
Question: Are Dubai property prices falling?
Answer: Average residential sales prices were 2.2% lower year-on-year in September 2026, although prices increased slightly quarter-on-quarter. Performance differs significantly by property type and community.
Question: Are Dubai rents falling?
Answer: Average rents remained 5.5% higher year-on-year in September, but growth has slowed. In Q3, 21.4% of rental transactions were agreed at a lower rent than the previous contract and another 38.7% were unchanged.
Question: What are average Dubai rental yields in Q3 2026?
Answer: Cavendish Maxwell reported average gross yields of approximately 6.6% for apartments and 4.9% for villas and townhouses.
Question: Is Dubai facing a property crash because of handovers?
Answer: Current data supports a more selective market adjustment rather than one uniform citywide crash. Supply-heavy segments face greater competition, while properties with stronger scarcity, end-user demand or differentiation can behave differently.
Question: Are buyers moving from off-plan to ready property?
Answer: Off-plan remains the larger segment by transaction count, but Q3 ready-property transactions rose 19.7% quarter-on-quarter and October ready apartment activity strengthened further. Buyers are increasingly comparing the two segments rather than automatically choosing new launches.
Question: What is the biggest property investment risk from new supply?
Answer: The biggest risk is usually not total Dubai supply but the number of directly comparable properties completing in the same community, building category and price range as the investment.
Conclusion: Dubai’s Handover Wave Is Creating a Selection Market, Not One Universal Outcome
The completion of approximately 38,000 homes during the first nine months of 2026 is already changing the balance of Dubai’s residential market.
Average sales prices are modestly lower than a year ago, transaction volumes have slowed from the exceptional levels of 2025 and tenants are gaining greater negotiating power as more completed homes become available.
At the same time, the evidence does not support a simple crash narrative.
Rental yields remain competitive. Ready-property activity strengthened quarter-on-quarter. Actual handovers continue to fall below headline scheduled supply. And individual communities are experiencing very different levels of competitive pressure.
The more important risk sits ahead. Nearly 292,000 homes are currently scheduled for 2027 and 2028 combined. Even if only part of that pipeline completes on schedule, investors will increasingly need to distinguish genuinely scarce assets from generic properties facing many substitutes.
2026 investor takeaway: Stop asking whether Dubai is oversupplied as one market. Ask how many comparable properties will compete with the exact unit you are buying. Stress-test the rent, remove assumed appreciation, calculate real net yield, verify the handover pipeline and compare the property with ready alternatives. In a delivery-heavy cycle, disciplined asset selection matters more than exposure to the Dubai market alone.